Sabeena Bubber Named to the 2026 Canadian Mortgage Hall of Fame
Sabeena Bubber • October 13, 2026

A career built on client relationships, industry leadership, and giving back

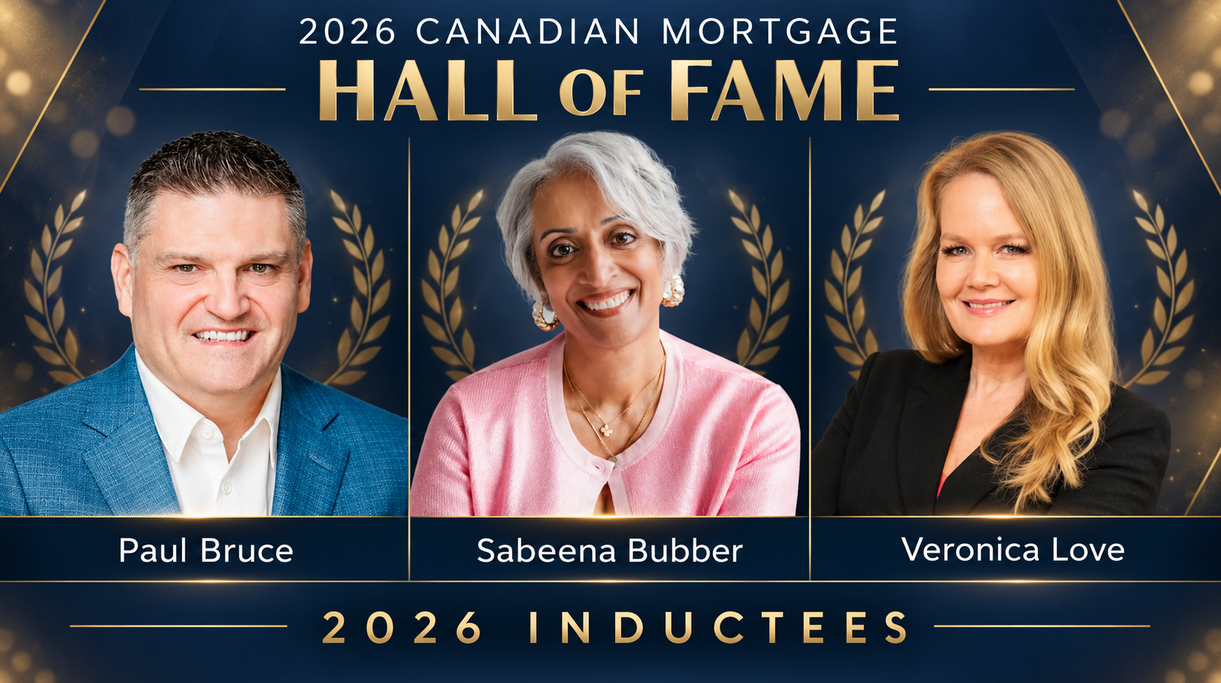
I’m incredibly honoured to share that I have been named one of the 2026 inductees into the Canadian Mortgage Hall of Fame by Mortgage Professionals Canada.


This recognition is especially meaningful because it reflects more than the mortgages I’ve funded or the awards I’ve received. It represents more than 30 years of working with individuals and families through some of their most important financial decisions, advocating for our industry, and finding ways to make a difference beyond the mortgage itself.

I’m grateful to be recognized alongside two respected industry leaders, Paul Bruce and Veronica Love, whose contributions have also helped shape Canada’s mortgage industry.


More Than $1 Billion in Mortgages Funded

Over the course of my career, I’ve helped more than 3,000 clients and funded over $1 billion in mortgages.

Those numbers represent much more than transactions. Behind every mortgage is a person, a family, or a business with goals, challenges, and plans for the future.


I’ve always believed that my role extends beyond finding a lender or securing an approval. It’s about understanding the bigger picture, helping clients make informed decisions, and building relationships that last well beyond the day a mortgage closes.

That philosophy has guided my work for more than three decades, and it continues to shape how I serve my clients today.


Giving Back Through Brokers Who Care

One of the most meaningful parts of my career has been the opportunity to support families facing difficult circumstances.

In 2016, I founded Brokers Who Care, a national initiative that brings mortgage professionals together to help families in crisis. Through the generosity and commitment of our community, the initiative has contributed more than $540,000 to support 75 families.

I have always believed that an industry built around helping people secure their homes has an opportunity to do even more for those who need support.


Brokers Who Care is one way we put that belief into action. It reminds me that our impact as mortgage professionals can extend far beyond our day-to-day work.


Supporting People Through Life’s Financial Transitions

I also founded The Divorce Circle, a platform designed to support people navigating separation and divorce.

Having experienced divorce myself and worked with countless clients facing major life transitions, I understand how overwhelming the financial side of these changes can be.


Questions about keeping the family home, qualifying for a mortgage independently, dividing property, or planning for the future can carry enormous emotional and financial weight.


The Divorce Circle brings together expert guidance, practical resources, and conversations that help people better understand their options. Through its podcast and educational content, it creates space for people to access information and support when they need it most.


For me, this work is a natural extension of what I do as a mortgage professional: helping people find clarity and move forward with greater confidence.


Advocating for Our Industry

Throughout my career, I’ve also been committed to strengthening the mortgage profession as a whole.

My involvement has included serving as an acting director with the Canadian Mortgage Brokers Association of British Columbia, participating in government advocacy, and contributing to industry discussions and events.

I believe a strong mortgage industry depends on knowledgeable professionals, high standards, open communication, and a willingness to keep learning.


When we share our experience and advocate for positive change, we help create a better environment for both mortgage professionals and the Canadians who rely on us.


An Honour That Reflects a Community

I’m deeply grateful for this recognition, but I also know that a career is never built alone.

I’ve had the privilege of working with wonderful clients, colleagues, lenders, and industry partners over the years. I’m thankful for the trust clients have placed in me and for the people who have supported the work I care so much about, including our community initiatives.


The Canadian Mortgage Hall of Fame recognizes professionals whose leadership, achievements, and service have contributed to the mortgage industry. To be included among those individuals is a tremendous honour.

The 2026 inductees will be recognized at the Canadian Mortgage Hall of Fame Gala during the National Mortgage Conference in Calgary.

As I reflect on more than 30 years in this business, one thing remains clear: the most meaningful part of this work has always been the people.


Whether I’m helping a family purchase a home, guiding a client through a complicated mortgage situation, or supporting families through Brokers Who Care and The Divorce Circle, my goal remains the same. I want to make a meaningful difference in people's lives.

Thank you to Mortgage Professionals Canada for this honour, and thank you to everyone who has been part of my journey. I look forward to continuing this work and finding new ways to support our clients, our communities, and our industry.

— Sabeena Bubber

SHARE THIS ARTICLE

RECENT POSTS
By Sabeena Bubber • October 7, 2026
How Mortgage Payment Frequency Affects What You Pay Over Time You’ve probably heard the saying that there are two certainties in life: death and taxes. When it comes to your mortgage, there’s really just one certainty—you’ll repay what you borrow, plus interest. What is flexible, though, is how often you make your mortgage payments. And that choice can have a meaningful impact on how quickly you pay down your mortgage and how much interest you pay over time. The Six Mortgage Payment Frequencies Most lenders offer the following payment options: Monthly – 12 payments per year Semi-monthly – 24 payments per year Bi-weekly – 26 payments per year Weekly – 52 payments per year Accelerated bi-weekly – 26 payments per year Accelerated weekly – 52 payments per year Standard Payment Frequencies The first four options are designed to align with how you get paid. For example: Paid monthly? Monthly mortgage payments may make sense. Paid every two weeks? Bi-weekly payments can align nicely with your cash flow. With these standard options, regardless of how often you pay, the total amount paid over the year is the same —it’s simply divided into more frequent payments. What Makes “Accelerated” Payments Different Accelerated payments work differently—and this is where the real savings happen. With accelerated bi-weekly or accelerated weekly payments, you’re paying a slightly higher amount each time. That extra money goes directly toward reducing your mortgage principal, which lowers the interest you’ll pay over the life of the mortgage. A Simple Example Let’s assume a $1,000 monthly mortgage payment: Monthly: $1,000 once per month = $12,000 per year Semi-monthly: $500 twice per month = $12,000 per year Bi-weekly: $1,000 × 12 ÷ 26 = $461.54 every two weeks = $12,000 per year Accelerated bi-weekly: $1,000 ÷ 2 = $500 every two weeks = $13,000 per year With accelerated bi-weekly payments, you effectively make two extra payments per year without having to think about it. Those extra payments reduce your principal faster, which lowers interest costs over time. Accelerated weekly payments work the same way—you just make smaller payments more frequently. Why This Matters Long Term While it’s difficult to calculate exact savings due to variables like interest rates, terms, and amortization changes, maintaining an accelerated payment schedule over the life of your mortgage can reduce your amortization by up to three years and save a significant amount of interest. The Bottom Line Accelerated payments are a simple, automatic way to lower your overall cost of borrowing—without needing to make lump-sum payments or drastically change your budget. If you’d like to see how different payment frequencies would impact your mortgage specifically, feel free to reach out anytime. I’d be happy to walk through the numbers with you and help you choose the option that fits your goals.
By Sabeena Bubber • September 30, 2026
Why More Mortgage Options Matter—Especially for Assignment Purchases One of the biggest advantages of working with an independent mortgage professional is access to choice. Instead of being limited to one lender and one set of products, mortgage brokers work with multiple lenders—each with different guidelines, risk tolerances, and mortgage solutions. That flexibility becomes especially valuable when your situation doesn’t fit neatly into a “standard” box. A great example of this is purchasing new construction through an assignment contract . Why Assignment Purchases Can Be Challenging Assignment purchases are often viewed as higher risk by traditional lenders. Rather than declining these deals outright, many lenders quietly make them difficult by adding layers of conditions, restrictions, or uncertainty. This can lead to delays, frustration, or financing falling apart late in the process. The Good News There are lenders—available exclusively through the broker channel —that have clear, favourable policies for assignment purchases. With the right lender and proper planning, these transactions are absolutely doable. Typical Financing Requirements for Assignment Purchases While every situation is unique, many lenders that allow assignment financing look for the following: Standard purchase qualification, including income verification, credit, and down payment Assignments accepted at either the original purchase price or current market value Minimum 620 credit score , with no prior bankruptcies or consumer proposals The full down payment must come from the purchaser —seller incentives cannot be used Required Documentation To secure financing, lenders typically require: The original purchase agreement signed by all parties The MLS listing (if applicable) The assignment agreement signed by the builder, original purchaser, and new buyer Any side agreements outlining changes to the purchase price A full appraisal to confirm value This list isn’t exhaustive, but it highlights that while assignment purchases require more coordination, they are very achievable with the right lender and guidance. Final Thoughts Assignment contracts can open doors to great opportunities—but only if your financing supports the transaction. This is where access to multiple lenders and specialized policies makes a real difference. If you’re considering purchasing new construction through an assignment, or if you’d like to explore more traditional purchase options, feel free to connect anytime. I’d be happy to walk you through the mortgage products available and help you choose an option that doesn’t limit your financing possibilities.
By Sabeena Bubber • September 23, 2026
Mortgage Options During Divorce or Separation: What You Should Know If you’re going through—or considering—a divorce or separation, you may not realize that there are mortgage solutions specifically designed to help one party keep the home . For many people, the family home is their largest asset and where most of their equity is tied up. In situations like this, a spousal buyout program can allow one person to refinance the property and buy out the other party’s share—often up to 95% of the home’s value . This option can work whether you want to keep the home or your former partner does. What Is the Spousal Buyout Program? The spousal buyout program is a refinancing option that allows one owner to purchase the other owner’s share of the property as part of a separation or divorce settlement. In some cases, it can also be used to pay off jointly held debts, as outlined in a legal agreement. Below are some of the most common questions about how the program works. Is a finalized separation agreement required? Yes. Lenders require a signed and finalized separation agreement that clearly outlines how assets and debts are to be divided. This document is essential for approval. Can the funds be used for renovations or personal debts? No. Funds from a spousal buyout can only be used to: Buy out the other owner’s share of equity Pay off joint debts specifically listed in the separation agreement They cannot be used for renovations, personal loans, or unrelated expenses. How much equity can be accessed? The maximum amount available is the amount required to: Buy out the other party’s agreed-upon share of equity Pay off any joint debts listed in the agreement This amount cannot exceed 95% loan-to-value . What is the maximum loan-to-value allowed? The maximum loan-to-value is the lesser of : 95%, or The remaining mortgage balance plus the required buyout and joint debt payout The property must be the primary owner-occupied residence . Do all parties need to be on title? Yes. All individuals involved in the buyout must currently be registered on title. Your solicitor will confirm this through a title search. Does this only apply to married or common-law couples? No. While commonly used for married or common-law couples, the program may also apply to siblings or friends who jointly own a property and need one party to exit the mortgage. These cases are typically reviewed on an exception basis and require insurer approval. If no separation agreement exists, the purchase contract must clearly outline the buyout terms. Is a full appraisal required? Yes. A physical, on-site appraisal is required to confirm the property’s value before the mortgage can be finalized. Final Thoughts This overview covers some of the most common questions about mortgage options during separation or divorce, but every situation is different. Working with an independent mortgage professional gives you access to multiple lenders, specialized programs, and unbiased advice—so you can clearly understand your options and choose what’s best for your future. If you’re navigating a separation and need guidance around keeping or selling the home, feel free to connect anytime. All conversations are handled with discretion and confidentiality, and I’d be happy to walk you through your options.