What Will Mortgage Financing Look Like In 2021?
Sabeena Bubber • October 21, 2020

There is no doubt that 2020 was one for the books. It will be remembered as a year like no other. COVID-19 has caused significant national economic disruption, to say the least. While we’ve seen government intervention, record unemployment, mortgage payment deferrals, record low-interest rates, we’ve also seen continued growth in the housing market.

So what can we expect as we complete the final quarter in 2020 and move into 2021? Well, low interest rates and increased scrutiny on all mortgage applications are most likely in the cards.

Low interest rates

Right now, both fixed and variable rate mortgage rates are at all-time lows. The cost to borrow money for a mortgage has never been cheaper. According to the Bank of Canada, we can expect them to stay low for the foreseeable future. “Interest rates are very low, and they are going to be there for a long time. Canadians and Canadian businesses are facing an unusual amount of uncertainty, so we have been unusually clear about the future path for interest rates.”

And while low interest rates are a good thing for financing property now, unfortunately, they won’t be as easy to access as in previous years.

More scrutiny on mortgage applications

While we don’t expect lender or insurer guidelines to change much in the coming months, securing mortgage financing in a post-COVID economy has already proven to be harder as lenders apply increased scrutiny to each application. Every mortgage application is being looked at more deeply, and additional documentation is being requested to substantiate your application. Lenders are being more cautious about who they’re lending money to.

If you’re self-employed or rely on overtime, bonuses, or picking up additional shifts to make ends meet, securing a mortgage is going to be more difficult for you. As lenders look at a 2 year average for employment, if you took a hit to your income in 2020, that will impact you in 2021. Any type of non-guaranteed income will be more scrutinized.

If the pandemic impacted your employment and you deferred any payments (credit card, loan, line of credit, or mortgage), expect to be questioned. Lenders will ask for your story; they will want to know why you had to defer payments and how you are now in a better financial position.

Unfortunately, one of the common complaints about getting a mortgage is that it is very document-intensive. Lenders want to see a lot of supporting documents for every mortgage application. And moving into mortgage financing in 2021, you can expect even more requests for supporting documents.

Have a plan in place

So while the housing market continues to grow and low rates make it a good time to buy, the best way to prepare for increased scrutiny and documentation on your mortgage application is to plan ahead.

If your mortgage is up for renewal, you’d like to refinance, or you’re planning on buying a new property, the best thing to do is to get started immediately. Getting together your documents will take time; having a plan on what that looks like is the way to go.

I would love to have a conversation and outline all your options. If you have any questions, please don’t hesitate to contact me anytime!

SHARE THIS ARTICLE

RECENT POSTS

By Sabeena Bubber • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
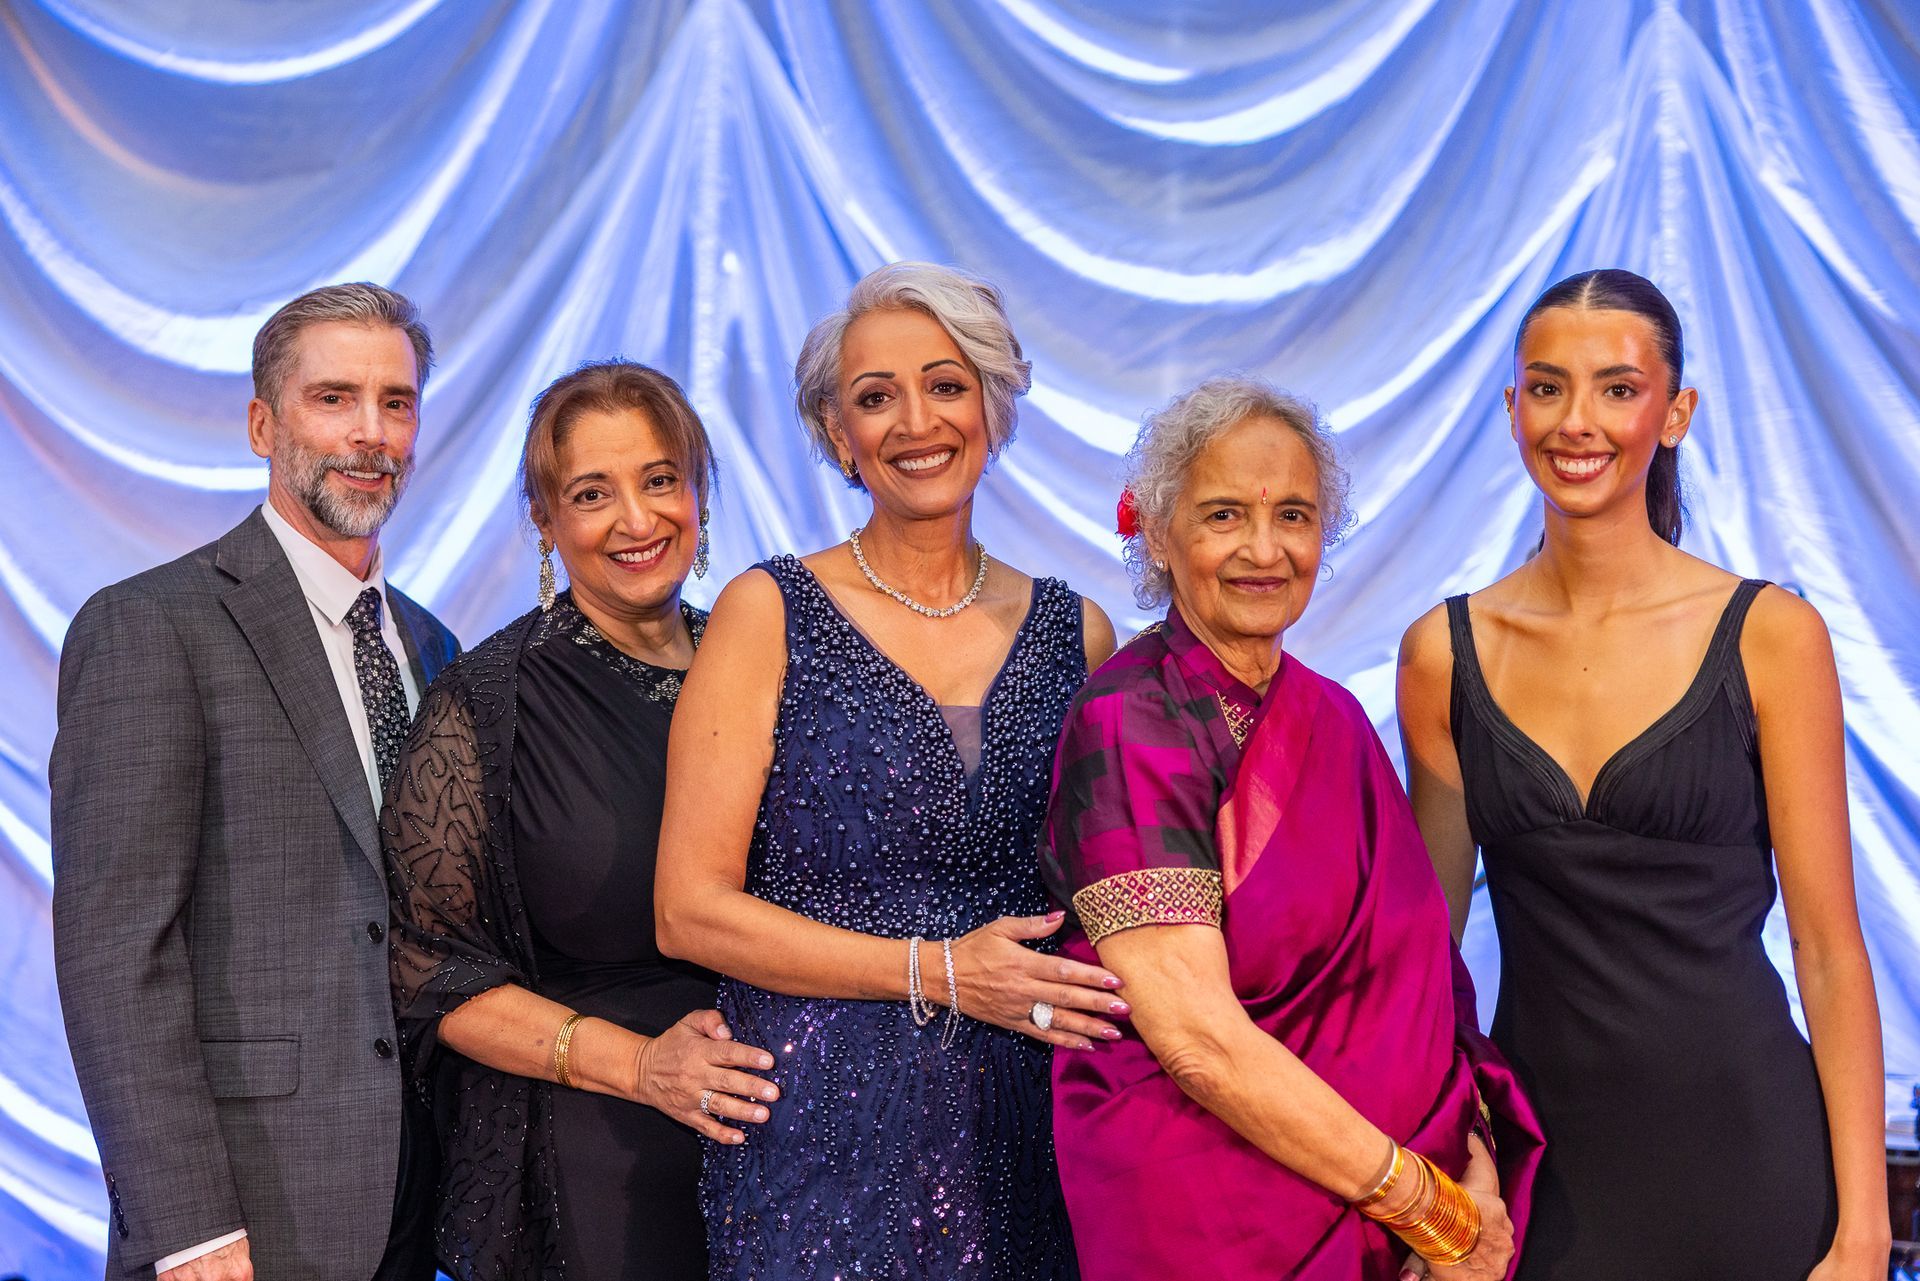
Sabeena and family at Canadian Mortgage Hall Of Fame
By Sabeena Bubber • October 24, 2026
Sabeena Bubber reflects on her Canadian Mortgage Hall of Fame induction, the journey behind it, and the people who made this meaningful milestone possible.
By Sabeena Bubber • October 21, 2026
Why the Property Matters When You’re Qualifying for a Mortgage When qualifying for a mortgage, lenders typically look at four core areas: Income Credit Down payment or equity The property itself Most buyers focus heavily on income, credit, and savings—and for good reason. But even if those boxes are checked, the property can still determine whether a mortgage is approved. Why Lenders Care About the Property From a lender’s perspective, the property is the collateral for the mortgage. In the unlikely event of default, they need to know the home can be sold quickly and at fair market value to recover their funds. Because of this, lenders are careful about the condition, value, and marketability of any property they finance. Homes that are in poor repair, unconventional, or overpriced can raise red flags—even when the borrower is well qualified. Appraisals Are Always Part of the Process Every mortgage requires an appraisal to confirm value. Insured mortgages (through CMHC, Sagen, or Canada Guaranty) often use an automated valuation model completed online. Conventional mortgages typically require a full, on-site appraisal by a certified appraiser. This appraisal is not optional and happens after an offer is accepted—not at the pre-approval stage. Why Pre-Approvals Aren’t a Guarantee A pre-approval is a great first step, but it only assesses you, not the property. Once you’ve made an offer, the lender must approve the specific home you’re buying. Understanding this upfront helps avoid surprises and confusion later in the process. The Risk of Buying Without a Financing Condition In competitive markets, buyers sometimes remove financing conditions to strengthen their offer. However, this comes with risk. If the appraisal comes back low—or the lender is concerned about the property’s condition—you could be denied financing after the offer is firm. In that scenario, your deposit may be at risk. Buying a Home That Needs Work If you’re considering a property that isn’t in perfect condition, there are solutions. A purchase plus improvements program allows you to buy a home and include renovation costs in your mortgage. The process is structured and requires planning, but it can be an excellent way to turn a fixer-upper into a great long-term investment. Final Thoughts Mortgage approval isn’t based solely on your finances—the property matters just as much. Knowing this ahead of time helps you make smarter offers, reduce risk, and plan more effectively. If you’re buying a property that needs work or want clarity on how a lender may view a specific home, feel free to reach out. I’d be happy to walk you through your options and help you plan with confidence.