Swedish Meatballs Recipe

sabeenabubber • February 10, 2015

Prep Time: 20 Minutes. Cook time: 1 hour. Yield: Serves 4 to 6.


  • I am proud to say that all of the recipes on my blog are Gluten Free.


All Swedish Goodness All the Time

Swedish Meatballs

In 2014 I took the girls to Sweden for the first time. I was concerned about how it would be on the Gluten Free side, but my best friend is Swedish and she said they were well prepared for us and that many people in Sweden are gluten free. WoW! Sweden is way ahead of the world (as always seems to be the case), within 10 minutes of leaving the airport, we were sitting in a McDonalds and the kids were eating their first ever Gluten Free Happy Meals. I was eating a gluten free Big Mac. Talk about mind blowing and the kids fell in love with Sweden immediately.


We went to a park by the name of Skansa, as we got hungrier we were trying to find gluten free lunch items for the girls. We ventured to a more formal (IKEA type) cafeteria where they were making gluten free pancakes and gluten free Swedish meatballs. Kavika ate a few bites of her pancake before she realized she should have ordered the meatballs. Since it’s so hard to find great gluten free foods they can indulge in, I went and got her some meatballs. The girls absolutely loved them and have been “pining” for them ever since.


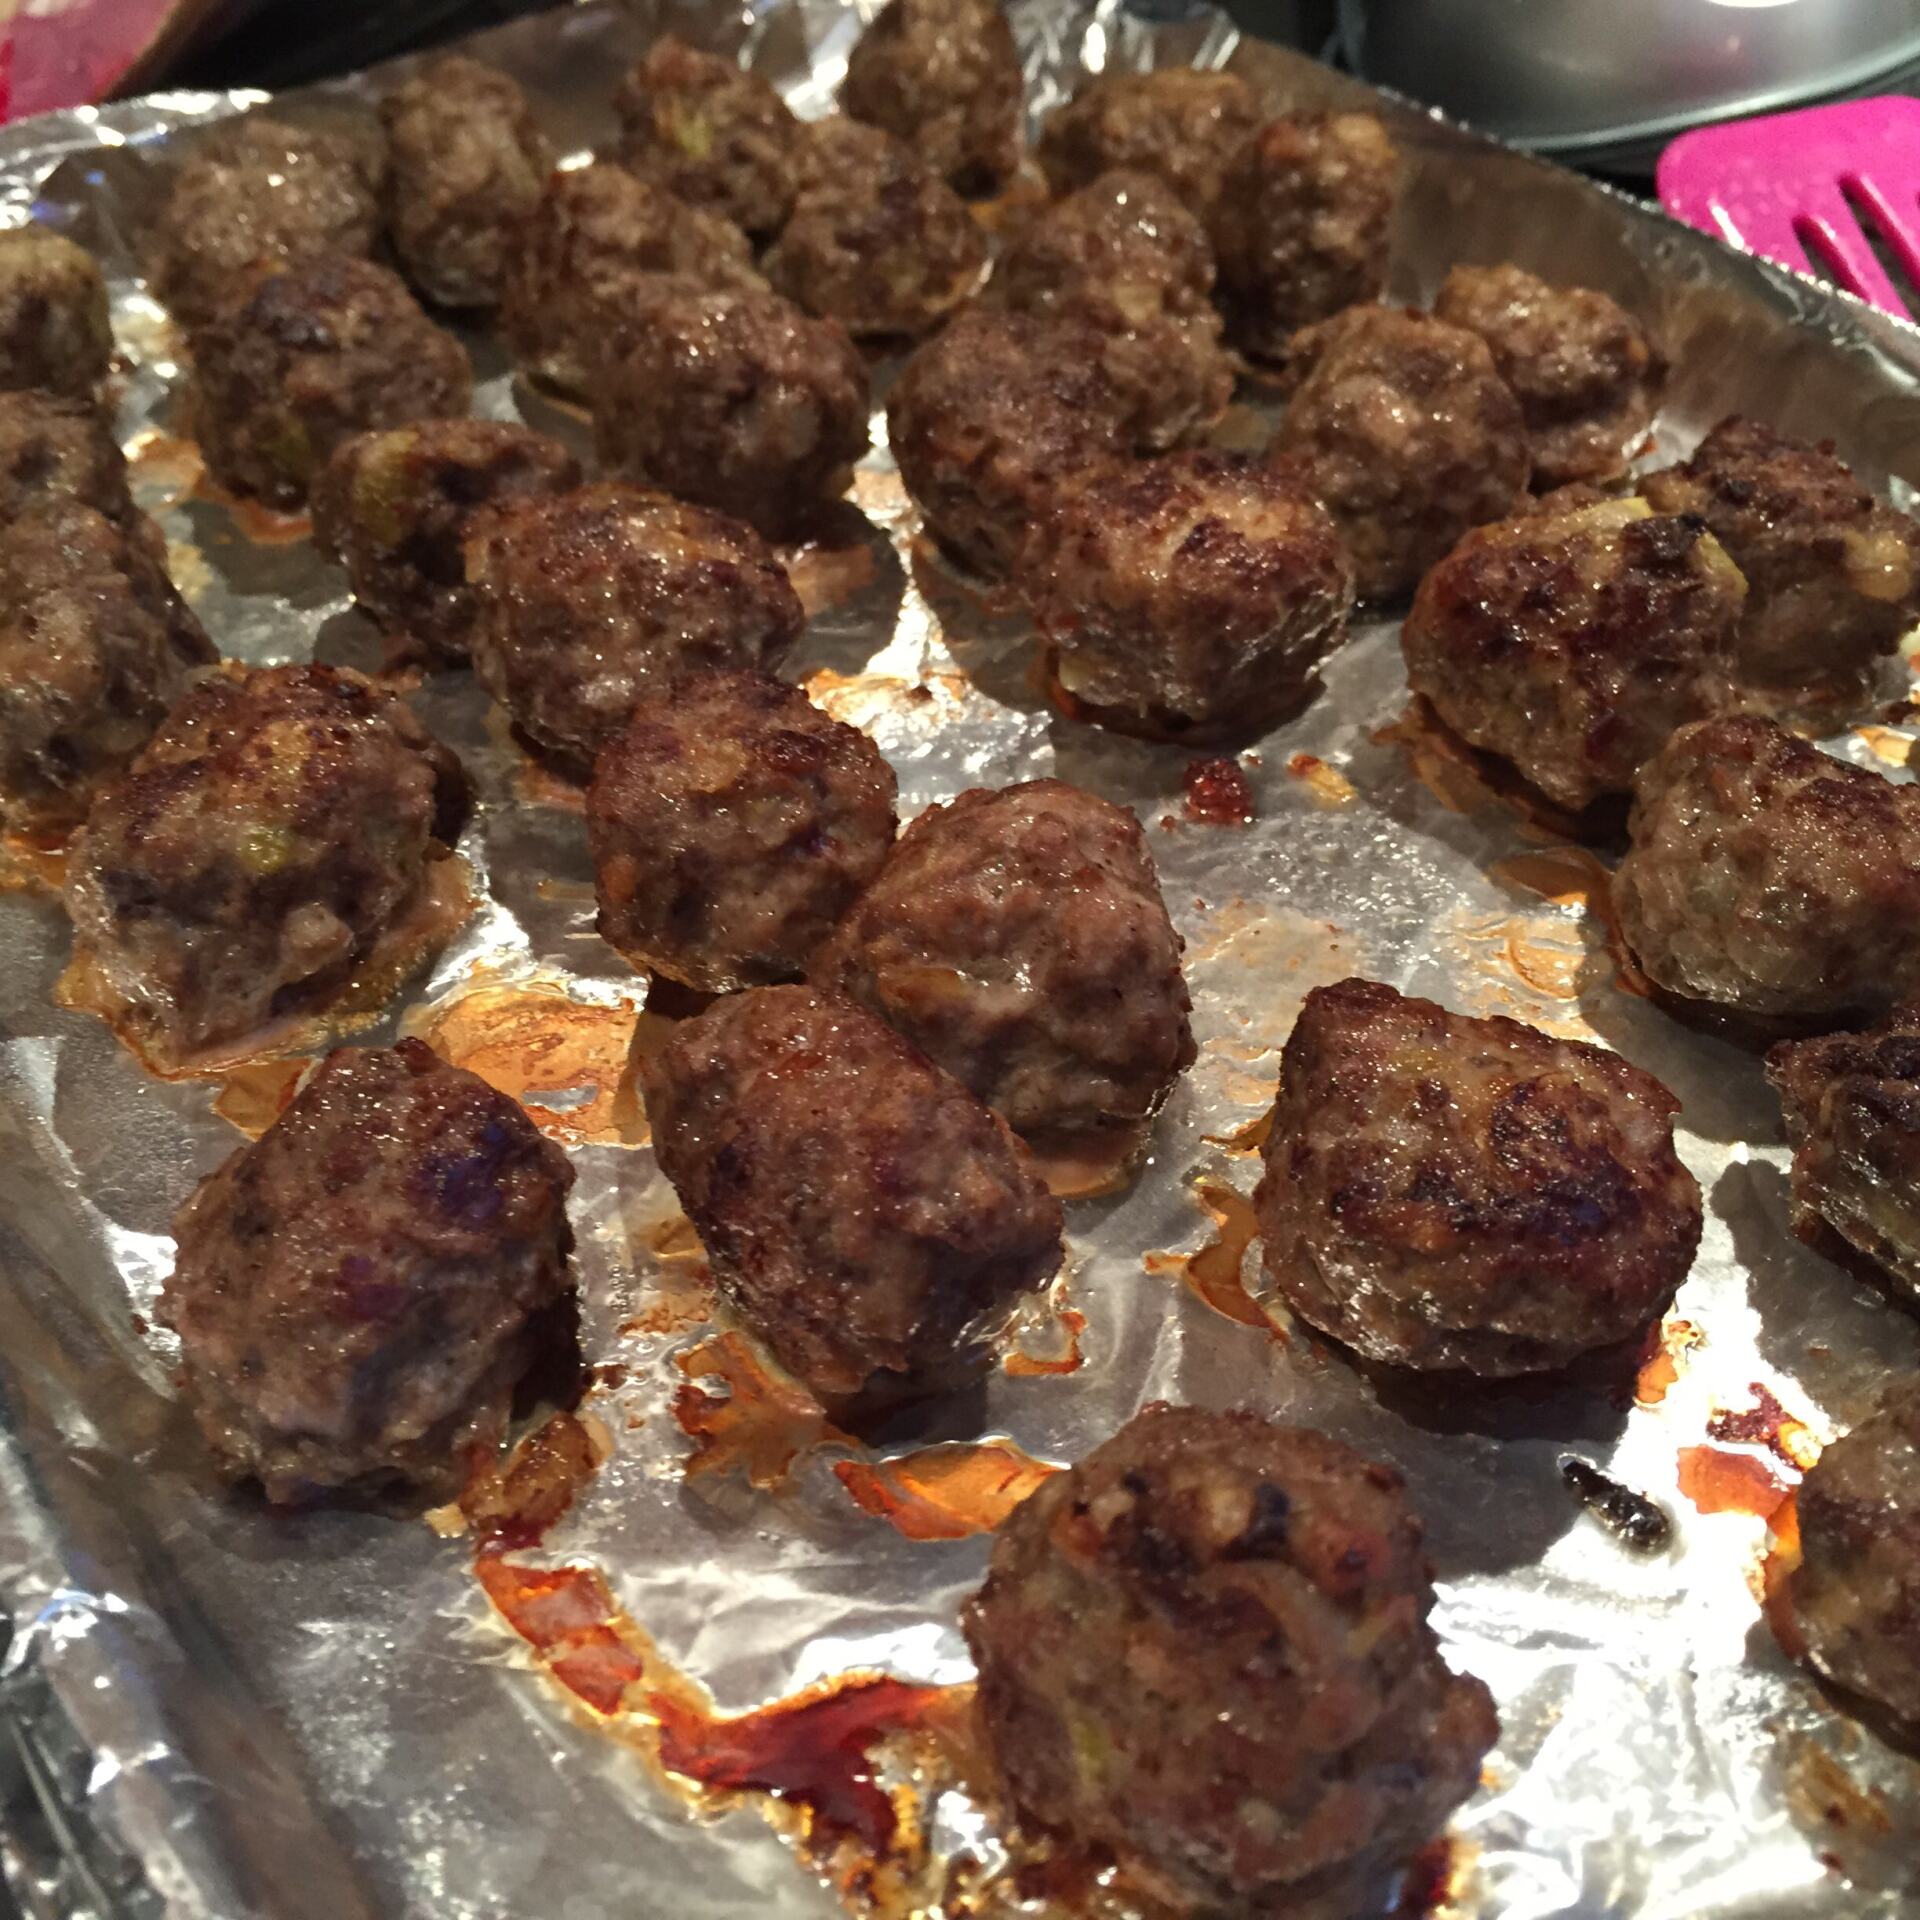
I’ve been trying to master a gluten free recipe and today, I finally had success! This is a shortcut recipe too. I used IKEA lingonberry Jam and I also purchase the IKEA packaged gravy which is gluten free as well. All I had to do was make the meatballs and the mashed potatoes. My oldest daughter took one bite and said, “this is the new love of my life!”, my youngest proclaimed, “I like these meatballs better than the ones in Sweden”, and my husband, he repeatedly told me how much he loved them.


Ingredients

Meatballs:

  • 2 Tbsp butter
  • 1 large yellow or white onion, finely chopped
  • 4 Tbsp Corn Starch
  • 2 eggs
  • 1 pound ground pork
  • 1 pound ground beef
  • 2 teaspoons kosher salt
  • ½ teaspoon freshly ground nutmeg
  • ½ teaspoon ground cardamom
  • 1 teaspoon black pepper


Sauce:

  • Graddsas gravy mix from IKEA
  • 280 ml water
  • 70 ml whipping cream


Method

1. Melt the butter in a sauté pan on medium-high heat. Stir in the chopped onions and cook until translucent and softened, 3-4 minutes. Set aside to cool.


2. Mix the eggs, salt, pepper, nutmeg, and cardamom. Add the ground beef and ground pork and use your (clean) hands to mix everything together until well combined. Add the onions at the end.

gf_swedish_meatballs (2) 2

3. Get a small bowl of warm water and dip your hands in them before making the meatballs. I find this an easy method to make the meatballs and avoid the meat from sticking to your fingers. Use your hands to form the meatballs about an inch-thick and place them on a plate or sheet pan. This recipe should make between 40 and 45 meatballs


4. Heat 6 Tbsp of butter in a large sauté pan on medium heat. When the butter is melted, add the meatballs to the pan. Cook the meatballs in batches so there is room to move and they don’t break down. Slowly brown the meatballs on all sides. Handle the meatballs gently so they do not break apart as you turn them.


Once the meatballs have browned on all sides, remove them from the pan and set aside on a cookie sheet. The meatballs don’t have to be cooked through at this point. I put them in the oven for another 20 minutes at 350 degrees


5. Follow the instructions to make the gravy mix.


gf_swedish_meatballs (3)
gf_swedish_meatballs (4)

6. Make mashed potatoes.


Pour gravy over the mashed potatoes and meatballs and be prepared to have a very happy family.


It’s rich but soooo delicious! Enjoy!


SHARE THIS ARTICLE

RECENT POSTS

By Sabeena Bubber September 16, 2026
Why the Source of Your Down Payment Matters More Than You Think When buying a home, most people focus on how much they need for a down payment. What often gets overlooked is that where the down payment comes from matters just as much to the lender . The source of your down payment affects approval, risk assessment, and how your mortgage is structured. Here’s why lenders care—and what you need to know. 1. Anti–Money Laundering Requirements Lenders aren’t just being cautious—they’re legally required to verify the source of your down payment. To comply with anti–money laundering regulations, lenders must document where every dollar of the down payment came from on every purchase. Acceptable Down Payment Sources Down payments can come from: Your own savings or investments Borrowed funds through an insured program (such as FlexDown) A gift from an immediate family member How You Prove the Source Personal savings: You’ll need bank statements showing the funds have been in your account for at least 90 days , or proof they were accumulated through payroll deposits or other acceptable sources. Borrowed funds: Any borrowed portion must be included in your debt service ratios , since you’re responsible for repayment. Gifted funds: A signed gift letter is required confirming the money is a true gift with no repayment obligation , along with proof the funds were deposited into your account. 2. Financial Suitability and Risk The source of your down payment also tells the lender a lot about your financial habits. Down payments coming from your own savings demonstrate: Positive cash flow The ability to save consistently Strong financial management This reassures lenders that you’re more likely to keep up with mortgage payments. If the down payment is borrowed or gifted, lenders may look more closely at the rest of your application to ensure the mortgage remains affordable. Why a Larger Down Payment Helps From a lender’s perspective, more equity equals lower risk. The more money you have invested in the property, the less likely you are to walk away from the mortgage. This reduces the lender’s exposure and can sometimes result in better terms. 3. Down Payment and Loan-to-Value (LTV) Your down payment directly establishes your loan-to-value ratio (LTV)—the percentage of the property’s value being financed. In Canada: Lenders can finance up to 95% of a property’s value The buyer must contribute at least 5% as a down payment Example: On a $400,000 purchase: Maximum mortgage = $380,000 Minimum down payment = $20,000 How the Source Affects LTV Property value must be genuine and independently supported. Lenders rely on appraisals and comparable sales—not artificial price inflation. If: The seller provides money back The buyer doesn’t bring the full down payment independently Funds move “behind the scenes” …the lender considers this a change to the LTV and may decline the mortgage. All financial details of the purchase must be fully disclosed. Non-disclosure is mortgage fraud , and lenders will not proceed if the numbers don’t align. Final Thoughts Lenders ask for detailed documentation about your down payment source for good reason—it affects legality, risk, and the structure of your mortgage. Understanding these rules upfront helps avoid delays, declined applications, and last-minute surprises. If you’d like to review your down payment options or talk through mortgage financing, feel free to connect anytime. I’d be happy to walk you through the process and help you plan with confidence.
By Sabeena Bubber September 9, 2026
This is a subtitle for your new post
By Sabeena Bubber September 2, 2026
The Bank of Canada announced today that it is holding its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%. While Canada's economic recovery is broadening, a new layer of uncertainty has entered the picture. Here is what happened and what it means for your mortgage.